

Small teams lose good people over perks they never knew they could afford. Most owners assume employee benefits for small business means private medical cover and a large budget. It doesn’t. Several of the most valued perks cost little beyond what the law already asks of you. This guide shows you which ones to pick and how to pay for them.
In this article, we’re going to discuss how to:
- Start with the benefits the law already requires
- Add low-cost perks that staff actually use
- Budget for each benefit before you announce it
Employee Benefits for Small Business: Start With the Legal Floor
Before adding anything, get the statutory basics right. Under automatic enrolment, you must put eligible staff into a workplace pension. The total minimum contribution is 8%, and your share is at least 3%, with the employee paying the remaining 5%. Contributions are usually based on earnings between £6,240 and £50,270 a year, according to GOV.UK.
Treat the pension as the first item in your employee benefits for small business package rather than a chore. Staff compare offers, and a clear explanation of what you pay in costs nothing to give. If you can afford to contribute above 3%, a modest step up is a visible, lasting signal that you take retention seriously. Check the thresholds each April, as they’re reviewed from time to time.
Low-Cost Perks That Cost Little Cash
Flexible Hours and Time Off
Flexibility costs payroll nothing. Let people shift start times, compress a week or work from home on set days where the job allows it. Agree the rules in writing so managers apply them evenly. An extra day off for a birthday or a volunteering day costs you one day of output, which is easy to budget.
Trivial Benefits
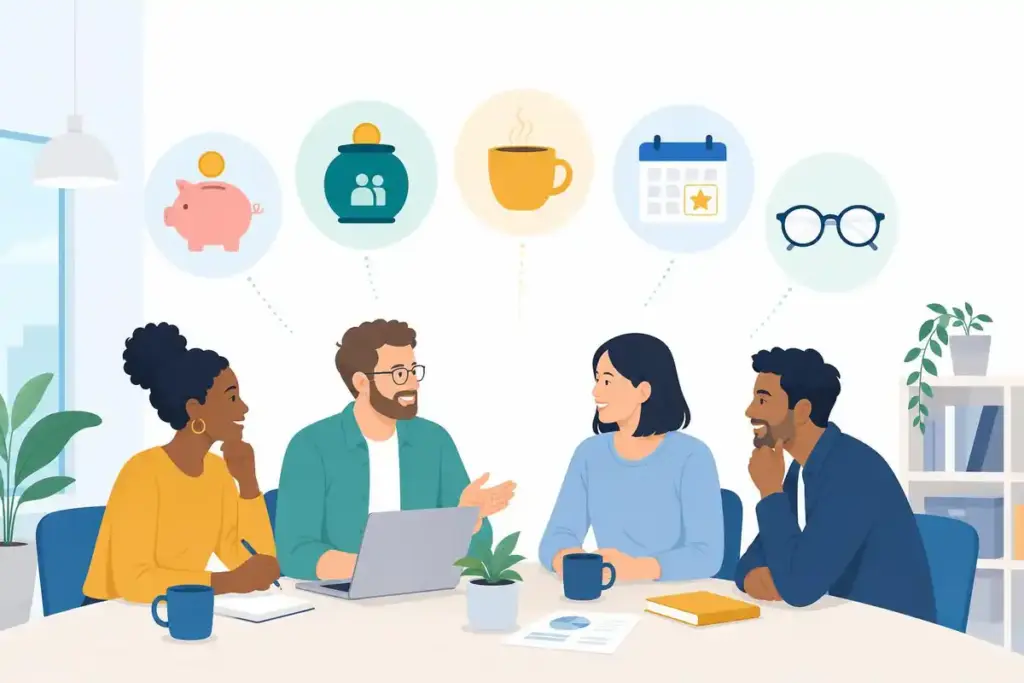
HMRC lets you give small gifts without tax or National Insurance when four conditions are met. The benefit must cost you £50 or less, it can’t be cash or a cash voucher, it can’t reward work or performance and it can’t be required by the contract. You needn’t report it to HMRC. Directors of close companies face a cap of £300 per tax year. A birthday hamper or a team lunch fits the rule neatly.
Eye Tests and Learning
If staff use display screens regularly, the Health and Safety Executive says you must arrange and pay for an eye test on request. You only pay for glasses when the test shows special glasses are needed for screen distance. A small learning budget per person, agreed up front, also costs far less than a replacement hire.
How to Choose Employee Benefits for Small Business Teams
Ask before you buy. A five-question survey tells you whether staff want flexibility, learning support or something else. Cost each option per head per year, then cap the total at a fixed share of payroll that you could defend in a bad quarter.
Start with two or three benefits, then review them after six months. Keep what gets used and drop what doesn’t. This sits alongside wider retention strategies such as pay reviews and clear progression. List your benefits in every job description you write, because candidates compare packages before they apply.
Benefits That Look Cheap but Aren’t
Some perks carry reporting duties. GOV.UK says employers usually must report expenses and benefits to HMRC and pay tax and National Insurance on them, with exemptions for some. Health insurance is one example it names. Check each proposed perk with your accountant before announcing it, because an unplanned tax bill can cost more than the perk itself.
Avoid promises you can’t sustain. Removing a benefit later damages trust faster than never offering it. The best employee benefits for small business budgets are the ones you can still afford in year three.
Conclusion and Takeaways
Affordable benefits come from choosing carefully, not spending widely. Start with the legal floor, add perks that cost time rather than cash and test each one against your accountant’s view of the tax position. For more practical ideas, browse our entrepreneurship guides.
- Treat the pension as your first benefit and explain it clearly
- Use flexible working and the £50 trivial benefit rule before costlier options
- Cost every perk per head and agree the tax treatment first
Frequently Asked Questions
What Is the Cheapest Benefit to Offer Staff?
Flexible working costs nothing in payroll terms, provided the role allows it. Agree clear rules so every manager applies it the same way.
Do I Have to Report Trivial Benefits to HMRC?
No, provided all four conditions are met, including the £50 limit per benefit. A benefit that fails any condition may need reporting, so check before you give it.
How Much Must I Pay Into a Workplace Pension?
Under automatic enrolment, the minimum employer contribution is 3% within a total minimum of 8%. In most schemes this is based on earnings between £6,240 and £50,270 a year.
Can Salary Sacrifice Help Me Offer More?
It changes the tax treatment, and GOV.UK says trivial benefits aren’t exempt when provided through salary sacrifice. Take advice from your accountant before setting one up.
Sources Consulted
- GOV.UK: Tax on trivial benefits
- GOV.UK: Workplace pensions, what you, your employer and the government pay
- GOV.UK: Reporting expenses and benefits, overview
- HSE: Eye tests for display screen equipment users
Disclaimer: This article is for information only and isn’t financial, tax or legal advice. Rules and thresholds change, so confirm current figures with GOV.UK or a qualified adviser.